A luxury home protection plan is a specialized high-value homeowners insurance program designed to cover the unique risks, elevated replacement costs, and lifestyle needs of premium properties that standard policies cannot adequately address. Known in the industry as high-value or high-net-worth home insurance, these plans are offered by carriers like Chubb, PURE (Privilege Underwriters Reciprocal Exchange), and AXA XL, and they go far beyond the coverage limits and service quality of conventional homeowners policies. If your home is valued at $750,000 or more in replacement cost, a standard policy almost certainly leaves you exposed. Understanding exactly what these plans cover, and how they differ from a luxury home warranty, is the first step toward protecting your investment with confidence.
What is a luxury home protection plan and what does it cover?
A luxury home protection plan, or high-value home insurance policy, covers expensive custom construction, higher-value belongings, elevated liability, and additional living expenses that exceed what standard policies provide. This is not simply a higher-limit version of a typical homeowners policy. The coverage structure, underwriting approach, and claims service are fundamentally different.
Guaranteed replacement cost
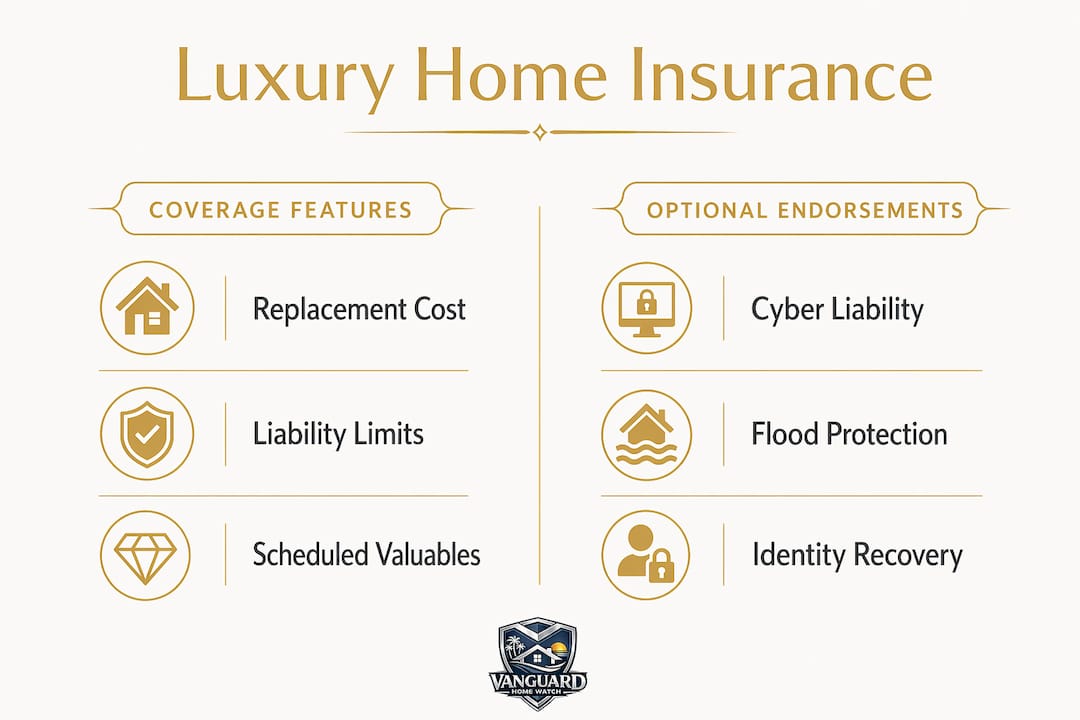
The most critical feature is guaranteed or extended replacement cost coverage. Guaranteed replacement cost pays to rebuild your home fully using premium materials and craftsmanship, even if rebuilding costs exceed your policy limits. Standard policies cap payouts at a stated dwelling limit, which can fall short when construction inflation or custom finishes drive rebuild costs higher. Some luxury carriers guarantee replacement cost up to $5 million, a figure no standard policy approaches.
Personal property and scheduled valuables
Luxury plans carry significantly higher personal property limits and allow you to schedule individual items such as fine art, jewelry, wine collections, and antiques for their full appraised value. Standard policies typically cap jewelry coverage at $1,500 to $2,500 without a separate rider. With a luxury plan, a single Patek Philippe watch or a commissioned painting can be individually listed and fully protected.
Liability and additional living expenses
Liability limits start around $1 million in luxury plans and can extend to tens of millions, reflecting real risk exposures from pools, guesthouses, and household staff. Standard policies offer $100,000 to $300,000, which is inadequate for affluent homeowners. Additional Living Expenses are often unlimited or set at very high thresholds, allowing you to maintain your lifestyle in comparable accommodations while your home is being restored. Standard policies limit ALE to 20 to 30 percent of the dwelling value.
Optional endorsements
Luxury policies include optional add-ons for cyber liability, flood, equipment breakdown, and identity theft recovery. These endorsements make premium home coverage customizable to your specific lifestyle, location, and risk profile.
| Coverage Feature | Standard Policy | Luxury Home Plan |
|---|---|---|
| Replacement cost | Capped at stated limit | Guaranteed, even above limit |
| Personal property | Low sublimits | High limits with scheduled items |
| Liability | $100K–$300K | $1M to tens of millions |
| Additional living expenses | 20–30% of dwelling value | Unlimited or very high |
| Optional endorsements | Limited | Cyber, flood, equipment, identity |
Pro Tip: Request a formal replacement cost appraisal from a certified appraiser before purchasing any luxury policy. Carriers like Chubb and PURE use their own valuation tools, but an independent appraisal gives you a documented baseline for negotiating coverage limits.
How does a luxury home protection plan differ from a luxury home warranty?
Terminology confusion leads many buyers to mistake a luxury home warranty for luxury insurance, and that mistake can create serious coverage gaps. These are two entirely different products with different triggers, costs, and purposes.
A luxury home warranty is a service contract that covers the repair or replacement of major appliances and home systems, such as HVAC units, plumbing, electrical systems, and kitchen appliances, when they fail due to normal wear and tear. A luxury home protection plan (high-value insurance) covers damage from covered perils such as fire, windstorm, water intrusion, and theft, along with personal liability and loss of use.
Here is where each product applies and where it does not:
- Insurance pays when a burst pipe floods your kitchen. A warranty does not cover flood or water damage from external sources.
- A warranty pays when your Sub-Zero refrigerator compressor fails after years of use. Insurance does not cover mechanical breakdown.
- Insurance is required by mortgage lenders as a condition of your loan. A warranty is entirely optional.
- Insurance covers catastrophic losses including total home destruction. A warranty has per-item caps and brand restrictions that may not cover premium appliances at full replacement value.
- Warranty costs typically range from $500 to $1,500 per year. Luxury insurance premiums vary widely based on home value, location, and coverage selections.
The practical takeaway: a luxury home warranty and a luxury insurance policy are complementary, not interchangeable. Owning both is the only way to address the full spectrum of risks a high-value home faces.
What practical considerations matter when selecting a luxury home plan?
Selecting the right premium home coverage requires more than comparing premium quotes. Several underwriting and policy management factors directly affect whether your coverage will perform when you need it most.
Insure for replacement cost, not market value. Your home’s market value reflects land, location, and demand. Replacement cost reflects the actual cost to rebuild with equivalent materials and labor. Rebuilding a luxury home can take 18 to 36 months and requires specialized contractors. Underwriting based on market value almost always results in underinsurance.
Schedule regular appraisals. Art, jewelry, wine, and antiques appreciate over time. A policy written three years ago may no longer reflect current values. Annual or biennial appraisals keep your scheduled items current and prevent disputes at claim time.
Add ordinance and law coverage. Building codes change. If your home is damaged and local codes require upgraded electrical, plumbing, or structural work during the rebuild, ordinance and law endorsements cover those additional costs. Without this endorsement, you pay the difference out of pocket.
Evaluate claims service quality directly. Ask prospective carriers how they handle luxury claims. Do they assign a dedicated adjuster? Do they have relationships with contractors who specialize in custom home restoration? The quality of claims service is as important as the policy terms themselves.
Avoid coverage fragmentation. Layering dwelling, scheduled valuables, and umbrella liability in one coordinated plan prevents gaps that appear when multiple carriers handle different pieces of your risk. Carriers like Chubb and PURE are designed to consolidate these coverages under one policy.
Pro Tip: When reviewing your policy annually, ask your broker to run a replacement cost estimator specific to your home’s square footage, finish quality, and custom features. Generic calculators underestimate luxury rebuild costs by a significant margin.
What high-touch service enhancements do luxury plans include?
The service experience with a luxury home protection plan is as distinctive as the coverage itself. Standard insurance companies process claims through call centers and assign rotating adjusters. Luxury carriers operate differently, and that difference matters enormously during a stressful loss event.
- Dedicated claims professionals are assigned to your account, not your claim. You work with the same person from the first call through final settlement, which eliminates the frustration of repeating your situation to a new representative at every step.
- Concierge-level claims support means your carrier coordinates directly with contractors, architects, and restoration specialists on your behalf. High-touch claims service with dedicated adjusters improves recovery quality and speeds the timeline for custom property restoration.
- Specialized contractor networks give luxury carriers access to craftspeople who understand custom millwork, imported stone, and specialty finishes. A standard contractor cannot replicate hand-painted ceilings or custom cabinetry. Luxury carriers maintain vetted networks that can.
- Proactive risk management consultations are offered by carriers like Chubb and PURE before a loss occurs. A risk manager visits your property, identifies vulnerabilities, and recommends mitigation steps. This service reduces your risk profile and can lower your premium.
- Faster claims resolution is a documented benefit of high-net-worth carriers. When your primary residence is uninhabitable, speed matters. Luxury carriers prioritize rapid assessment and interim housing arrangements to minimize disruption to your daily life.
How do luxury home plans integrate with broader property protection?
A luxury home protection plan is one layer of a complete risk management strategy, not the entire strategy. The best home protection plans work alongside other tools to eliminate the gaps that insurance alone cannot fill.
| Protection Layer | What It Covers | What It Does Not Cover |
|---|---|---|
| Luxury home insurance | Perils, liability, personal property | Wear and tear, mechanical failure |
| Luxury home warranty | Appliance and system breakdowns | Perils, liability, structural damage |
| Home watch service | Vacancy monitoring, early issue detection | Insurance claims, repairs |
| Security systems | Intrusion deterrence, monitoring | Physical property damage after the fact |
Professional home watch programs offer monitoring, concierge support, and maintenance coordination that is particularly valuable for luxury estates left vacant during seasonal absences. A home watch professional identifies a slow roof leak, an HVAC failure, or humidity buildup before it becomes a six-figure insurance claim. That early detection protects your property and your claims history. For seasonal residents in Naples and Southwest Florida, home watch services for seasonal owners represent a practical and cost-effective complement to any insurance program.
Key takeaways
A luxury home protection plan delivers guaranteed replacement cost, elevated liability, and concierge-level claims service that standard homeowners insurance cannot match for high-value properties.
| Point | Details |
|---|---|
| Guaranteed replacement cost | Covers full rebuild with premium materials, even above stated policy limits. |
| Insurance vs. warranty distinction | Insurance covers perils and liability; warranties cover appliance wear and tear. |
| Ordinance and law coverage | Add this endorsement to avoid out-of-pocket costs for code-required upgrades during rebuilds. |
| Concierge claims service | Dedicated adjusters and vetted contractor networks are as valuable as the policy terms themselves. |
| Layered protection strategy | Combine insurance, a home warranty, and professional home watch to eliminate all coverage gaps. |
Why I believe most luxury homeowners are underprotected
I spent years in law enforcement, and one thing that experience teaches you is that problems rarely announce themselves in advance. The same is true for luxury home risk. Most of the homeowners I speak with in Naples carry policies that were written years ago, based on outdated valuations, with coverage limits that have not kept pace with construction costs or the appreciation of their personal property.
The standard insurance industry is not built for luxury homes. It is built for volume. When you file a claim on a $3 million custom residence, you do not want a rotating call center adjuster who has never seen hand-laid marble or custom impact windows. You want someone who understands what it costs to restore your home to its original condition, and who has the contractor relationships to make that happen.
My honest recommendation: treat your insurance review the same way you treat your financial planning. Do it annually, with a broker who specializes in high-net-worth clients. Verify your replacement cost estimate every two years. Add ordinance and law coverage if you do not already have it. And do not rely on insurance alone. A policy pays after a loss. A luxury home watch service helps prevent the loss from reaching that scale in the first place. That combination, proactive monitoring plus strong insurance, is the most reliable protection strategy I have seen for high-value properties.
— Joseph
Protect your Naples home with Vanguard Home Watch LLC
Insurance covers what happens after a problem becomes a crisis. Vanguard Home Watch LLC helps prevent that crisis from developing in the first place. We conduct weekly visual inspections of vacant and seasonal luxury homes throughout Naples, North Naples, and Ave Maria, Florida, checking for water leaks, HVAC failures, humidity concerns, mold, pest activity, storm damage, and security issues. Every visit produces a detailed digital report with photos delivered directly to you. We are fully insured, bonded, background checked, and accredited members of the National Home Watch Association (NHWA). Explore our Naples luxury home watch services and see how proactive monitoring completes your protection plan.
FAQ
What qualifies a home for a luxury protection plan?
Most carriers define luxury or high-value homes as properties with a replacement cost of $750,000 or more. Eligibility also depends on construction quality, custom finishes, and location.
Is a luxury home protection plan the same as homeowners insurance?
Yes, but it is a specialized tier of homeowners insurance. It offers guaranteed replacement cost, higher liability limits, and concierge claims service that standard policies do not include.
Do I need both a luxury home warranty and a luxury insurance plan?
Yes. Insurance covers perils and liability while a warranty covers appliance and system breakdowns from wear and tear. The two products address different risks and work best together.
How often should I review my luxury home insurance policy?
Review your policy annually and update scheduled valuables after any new appraisal. Replacement cost estimates should be recalculated every two years to account for construction cost inflation.
How does home watch service relate to my luxury home insurance?
Home watch services identify developing issues like leaks or HVAC failures before they escalate into major claims. Early detection protects your property condition and helps preserve a clean claims history with your insurer.

